1
7:58 · Before the office opens
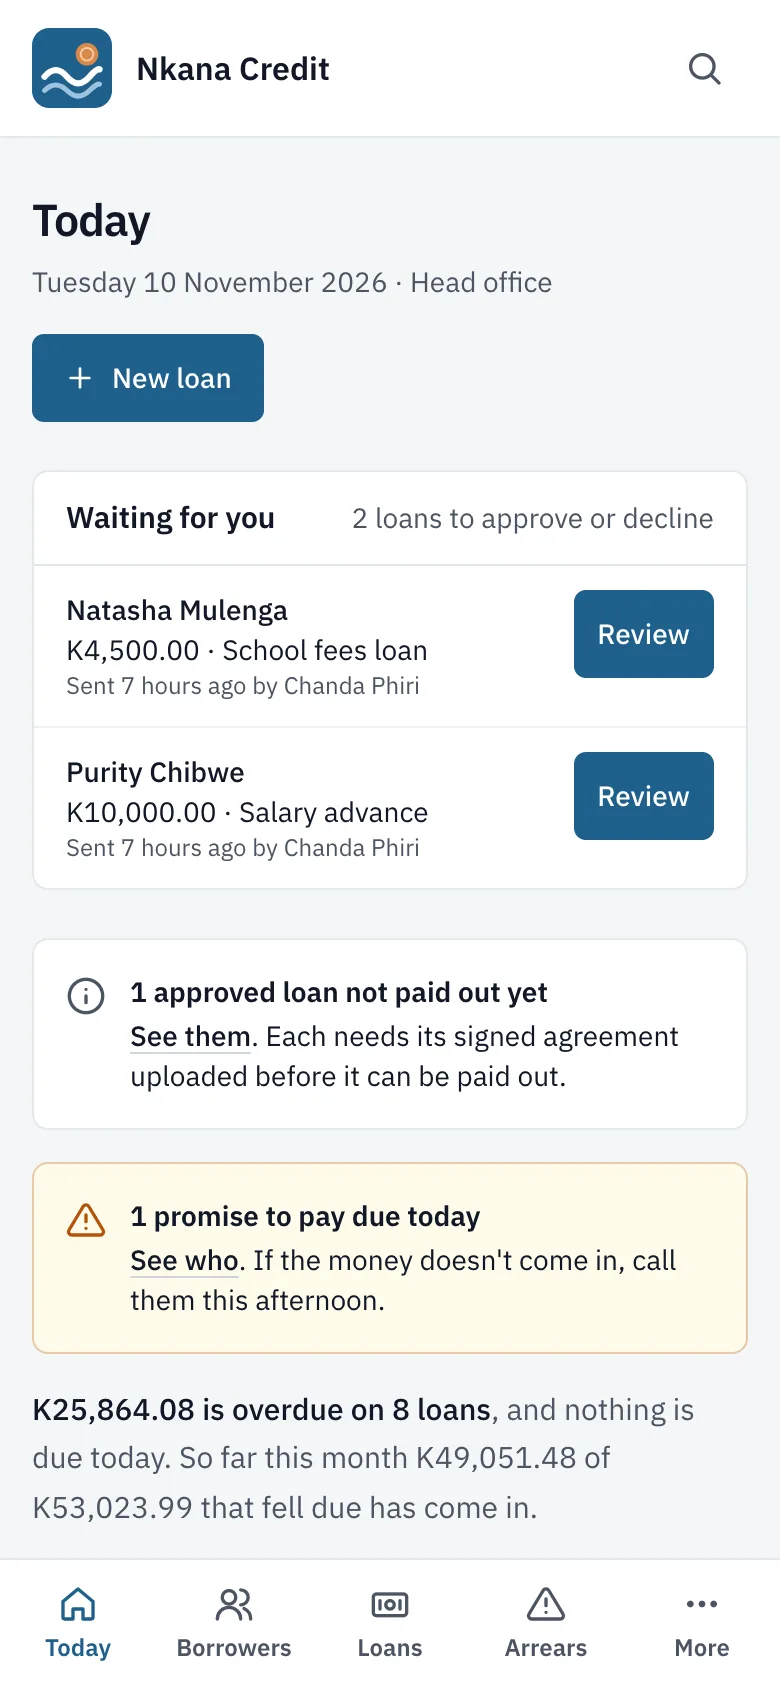
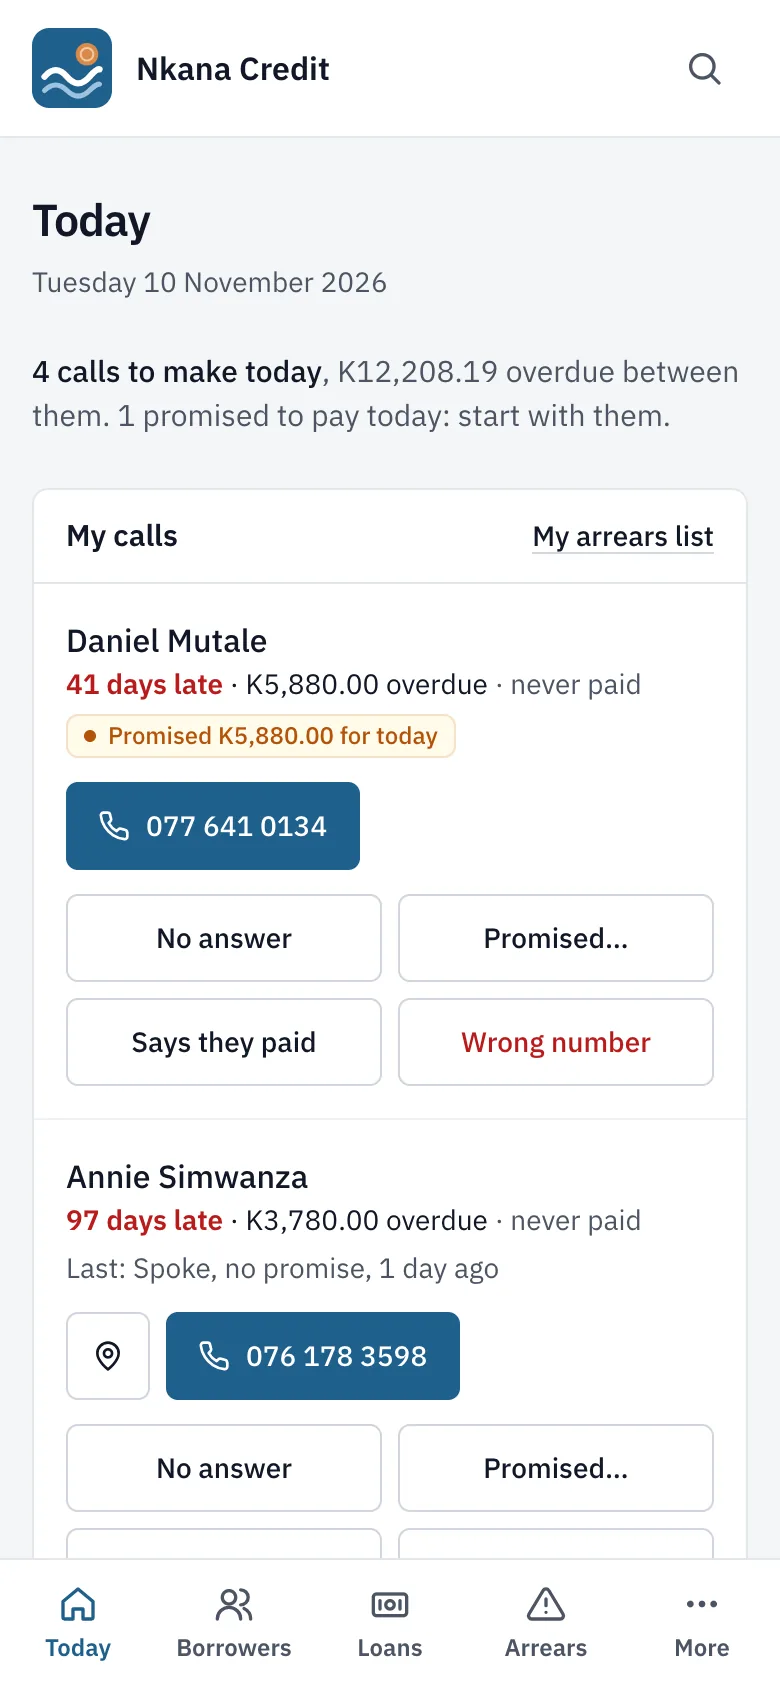
Today: the day's list
Loans waiting for approval, promises to pay that fall due, what has come in, how much is late, and the calls to make, most overdue first.
- Collected today and this month, against what fell due
- Behind on payments, in money and number of loans
- At risk: the share of the book more than 30 days late
- Coming up this week, with the number to call
2
8:40 · A borrower walks in
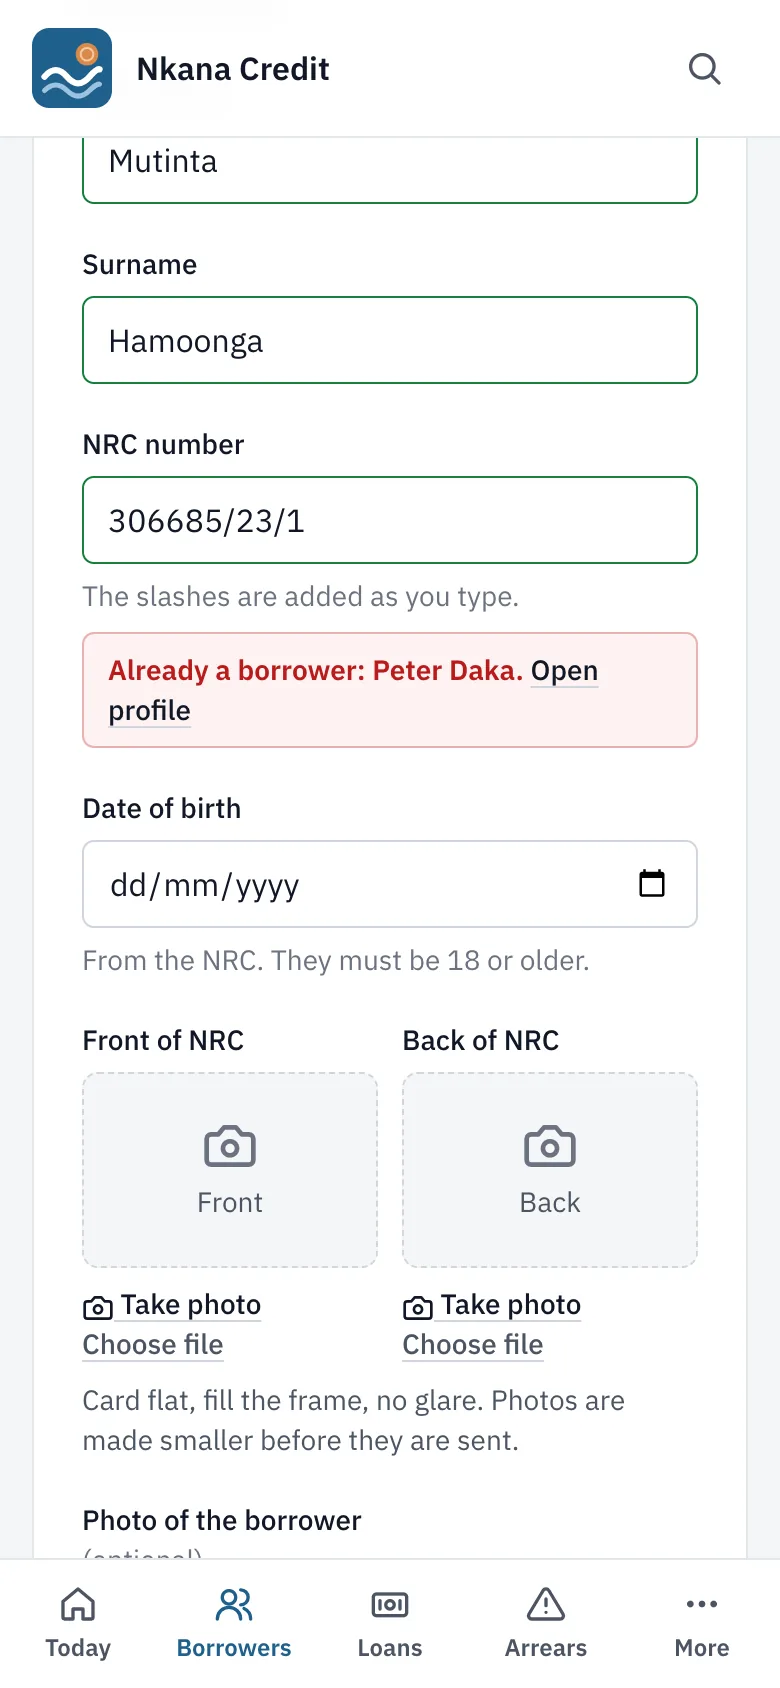
Add a borrower in one short form
The ID number is checked as it is typed, so the same person can't be registered twice under a new name. Documents are photographed with the phone's camera.
- ID card front and back, payslip and borrower photo
- 18 or older, checked from the date of birth
- Home location saved, so a collector can find the house
- Blacklist with a reason, so nobody lends to them again
3
9:05 · Writing the loan
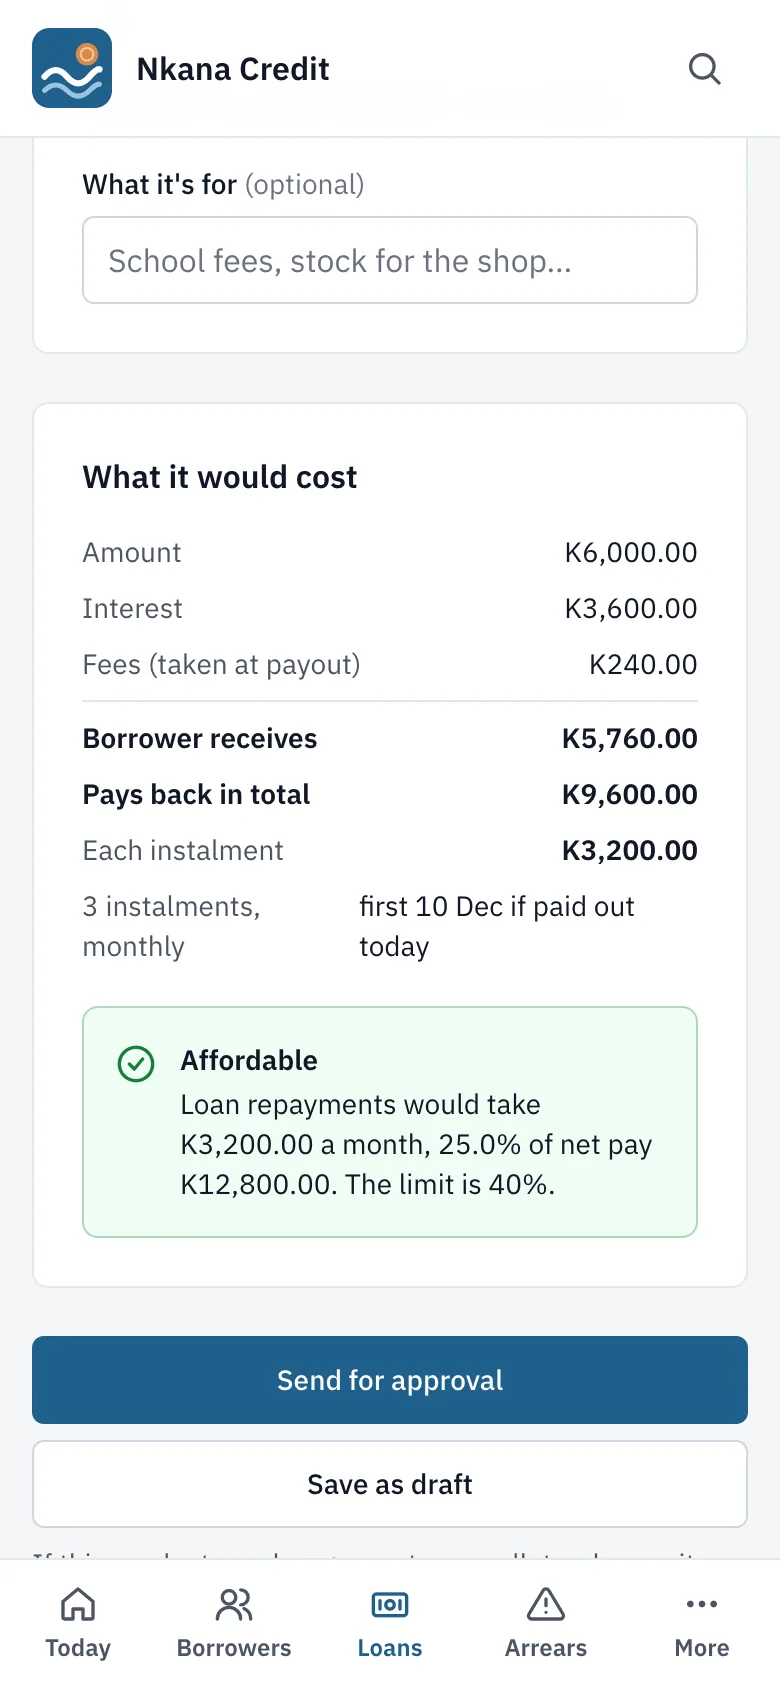
The cost and schedule before it goes out
Choose the borrower, the product and the amount. Interest, fees, every instalment and whether they can afford it are worked out on the spot, the same way every time.
- Your own products: rates, fees, limits and terms
- Flat, reducing balance or a fixed fee
- Daily, weekly, fortnightly or monthly instalments
- Guarantors and collateral, with photos
4
9:30 · A manager decides
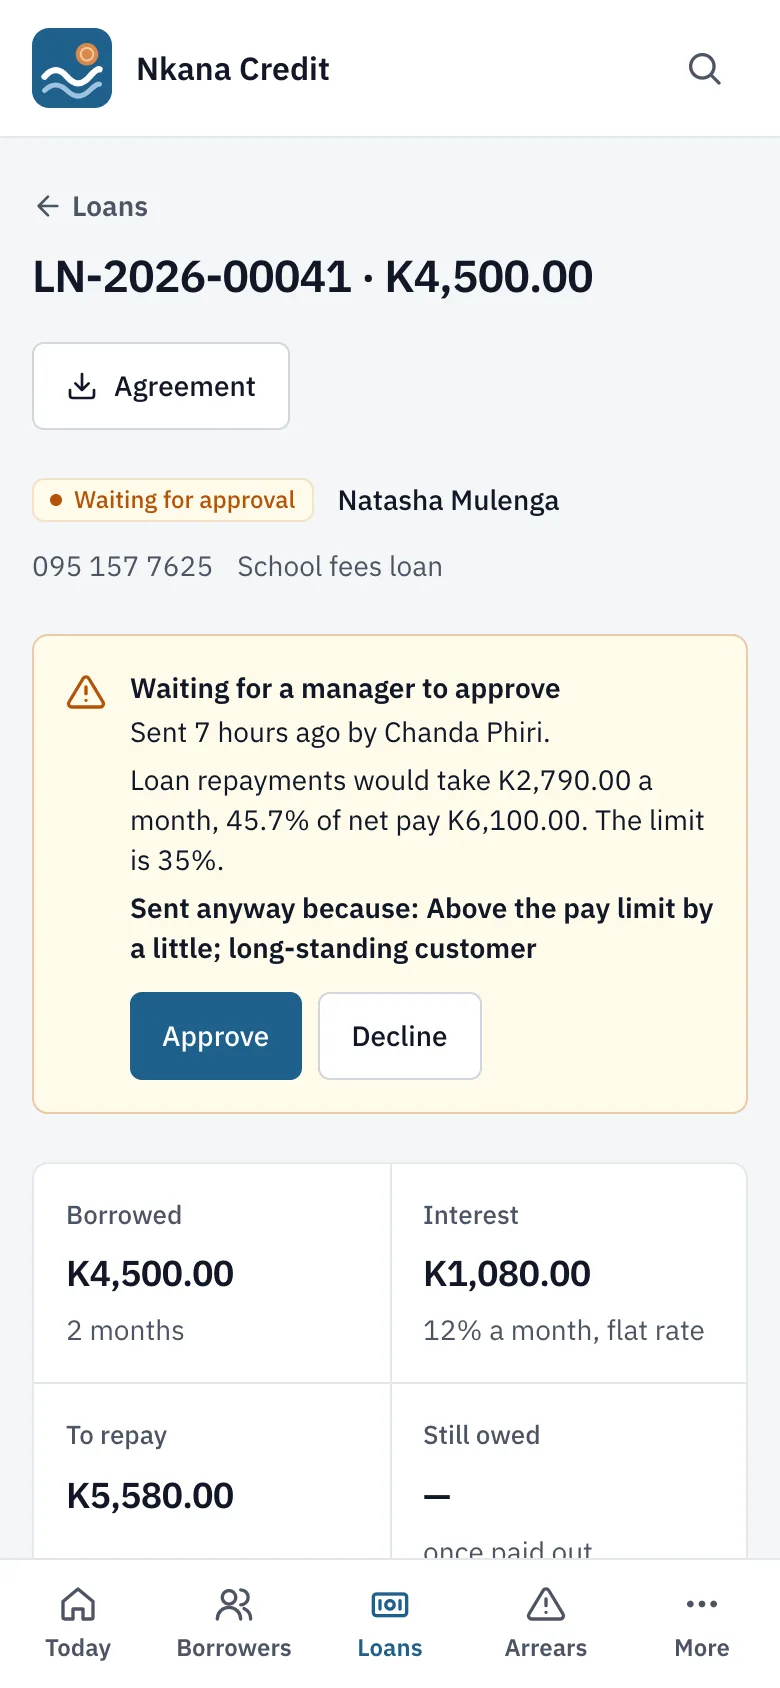
Approval by a manager
The manager sees the loan straight away, with the affordability result and the officer's reason, and approves or declines it in one tap.
- Someone else approves what an officer wrote
- Approval limits per manager
- Printed agreement with the schedule and signature lines
- No payout until the signed copy is photographed and kept
5
11:15 · Money comes in
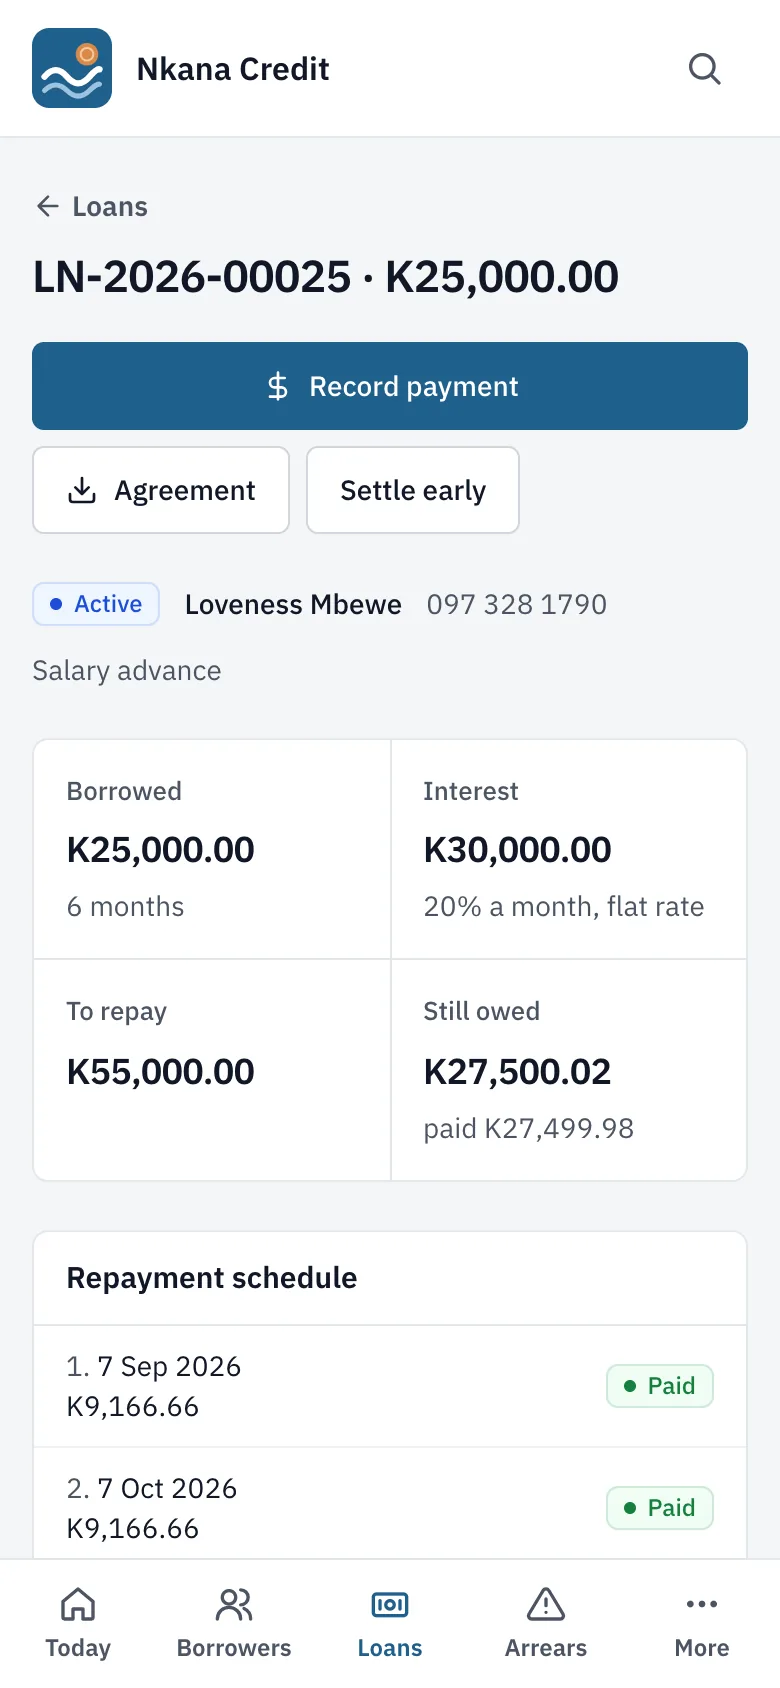
Record a payment and print the receipt
Cash, mobile money, bank or payroll. The money goes against the oldest instalment first, the balance updates, and a numbered receipt is ready.
- Transaction ID required for mobile money and bank
- Paying early and paying off the whole loan
- Penalties added by your own rules after grace days
- Reversing a payment needs a reason and stays on record
6
13:40 · After lunch
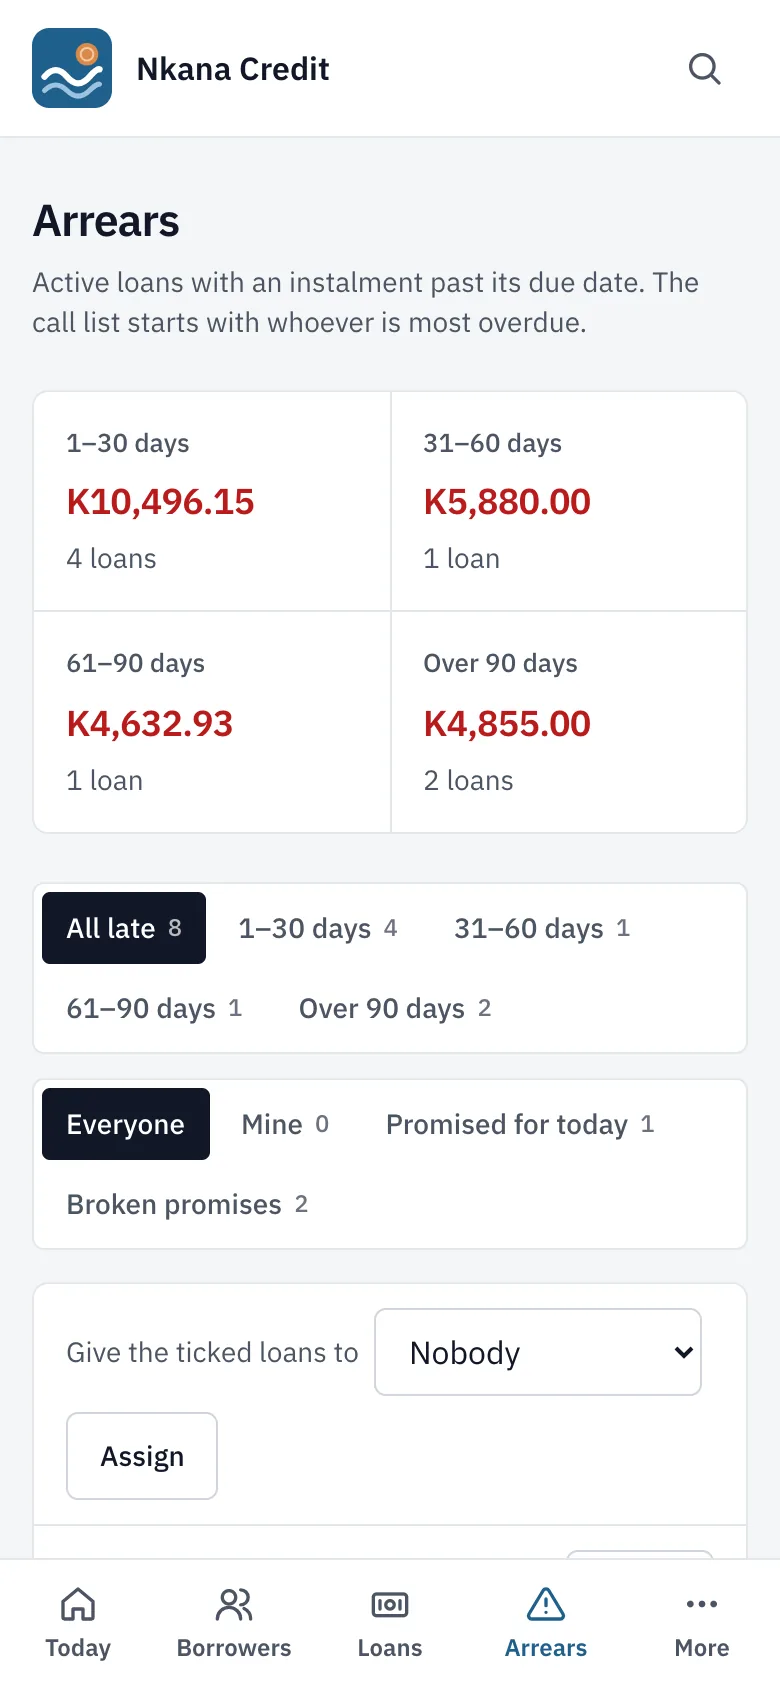
Arrears, by how late
Every late loan, grouped 1–30, 31–60, 61–90 and over 90 days, with who is following it up and any promise to pay.
- Give loans to a collector with a tick
- Promises to pay come back on the day they are due
- Broken promises one tap away
7
14:25 · Out in the field
The collector's call list
Each collector signs in to their own list for the day and records the result of every call or visit in one tap.
- Call, visit, promise or wrong number, each one tap
- Directions to the saved home location
- Their own list, nobody else's
8
16:00 · Reminders go out
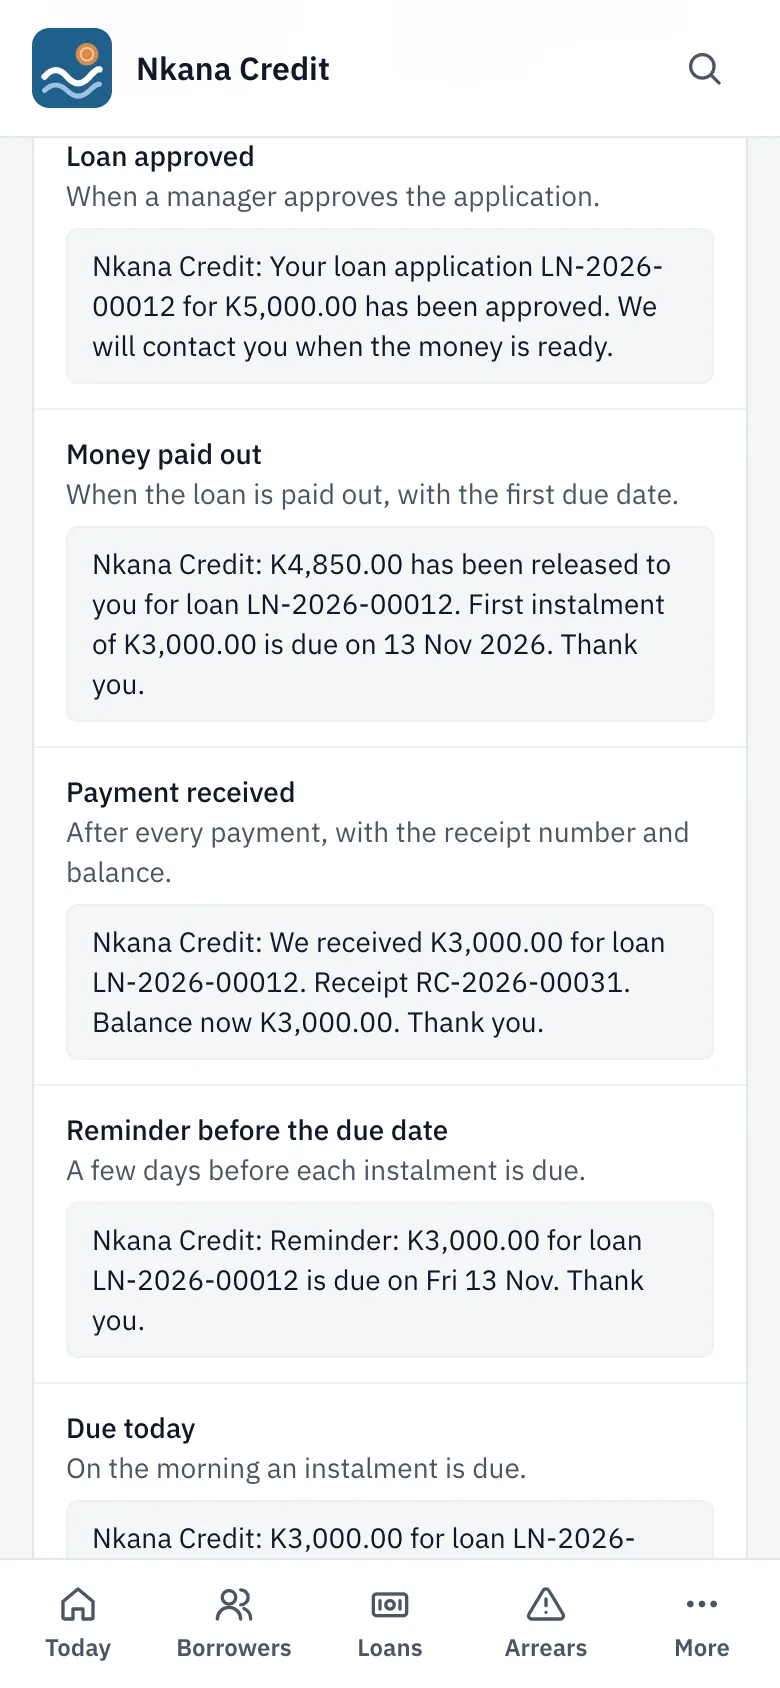
Reminders and receipts by text
A text a few days before each instalment, on the day it is due, when it is overdue, and after every payment with the new balance. You choose which go out.
- Sent under your name
- In Zambia through our gateway; elsewhere through a provider in your country
9
17:30 · Closing the day
Reports
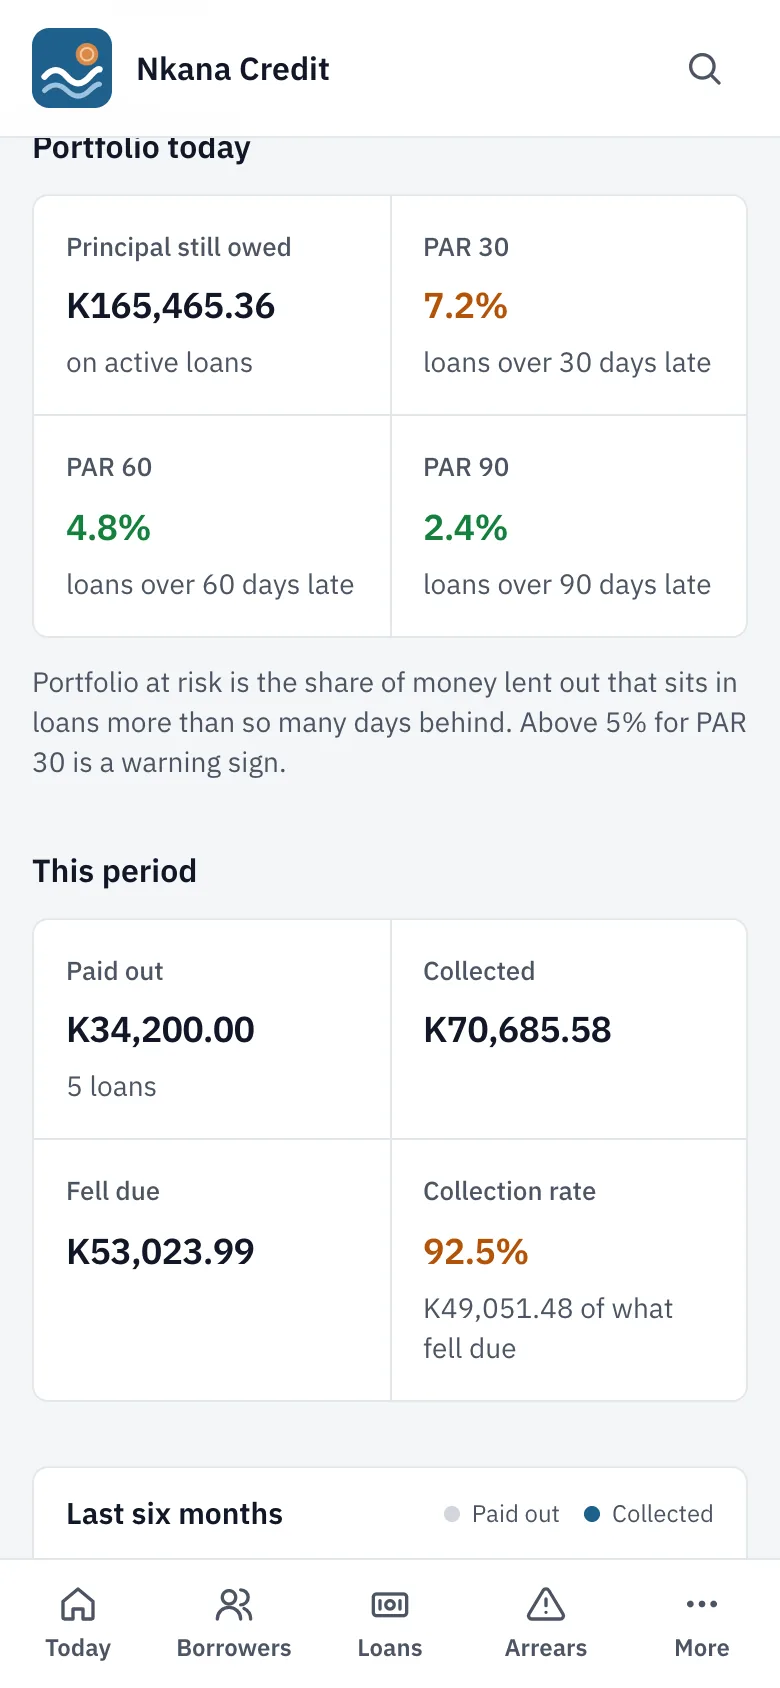
What was lent, what came in, the collection rate and the portfolio at risk, for any dates, by product and by loan officer.
- PAR 30, 60 and 90
- Last six months, paid out against collected
- Each officer's loans and how they are doing